GST:
In case the export of goods which are subjected to export duty, but rate of duty is nil or exempted, said export can be considered for the purpose of refund of accumulated ITC.
[Circular No. 160/16/2021-GST]
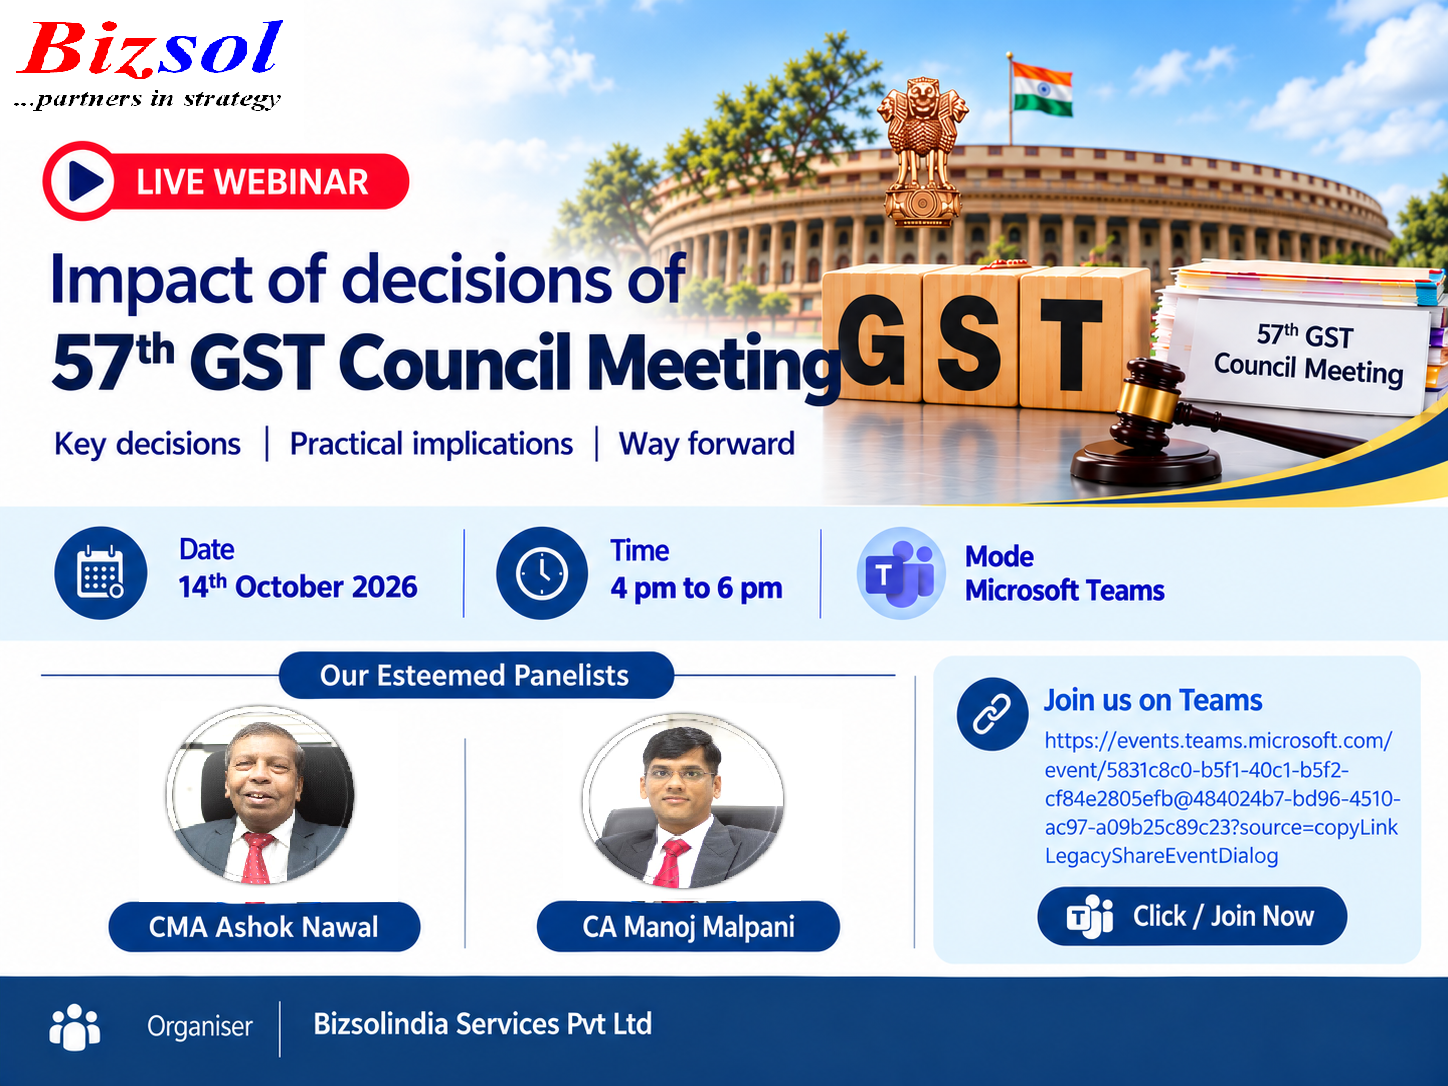
webinar on “Impact of Decisions of the 57th GST Council Meeting” on 14th October 2026 at 4:00 PM to 6:00 PM
This will close in 20 seconds