Daily Updates

Income Tax: The Central Board of Direct Tax (CBDT) has issued circular which provides comprehensive guidelines on condoning delays in filing income tax returns (ITRs) that claim refunds or seek to carry forward losses under Section 119(2)(b) of the Income-tax Act, 1961.(03.10.2024)

The Central Board of Direct Tax (CBDT) has issued circular which provides comprehensive guidelines on condoning delays in filing income tax returns (ITRs) that claim refunds or seek to carry forward losses under Section 119(2)(b) of the Income-tax Act, 1961. This circular supersedes all previous instructions and sets clear procedures for handling such delays. Key …
Income Tax: The Central Board of Direct Tax (CBDT) has issued circular which provides comprehensive guidelines on condoning delays in filing income tax returns (ITRs) that claim refunds or seek to carry forward losses under Section 119(2)(b) of the Income-tax Act, 1961.(03.10.2024) Read More »

Income Tax: The Central Board of Direct Tax (CBDT) has specified ‘Principal Secretary to Government & Chairman, Odisha Computer Application Centre (OCAC), Department of Electronics & Information Technology (E&IT), Government of Odisha’ for the purposes of identifying genuine beneficiaries for social welfare schemes of the Government of Odisha.(03.10.2024)

Income Tax The Central Board of Direct Tax (CBDT) has specified ‘Principal Secretary to Government & Chairman, Odisha Computer Application Centre (OCAC), Department of Electronics & Information Technology (E&IT), Government of Odisha’ for the purposes of identifying genuine beneficiaries for social welfare schemes of the Government of Odisha. [Notification No. 106/2024 dtd. 01-10-2024]

RBI: The Reserve Bank of India (RBI) has issued circular that mainly focuses on the updated provisions related to compounding of contraventions under the FEMA (Foreign Exchange Management Act), 1999.(02.10.2024)

RBI The Reserve Bank of India (RBI) has issued circular that mainly focuses on the updated provisions related to compounding of contraventions under the FEMA (Foreign Exchange Management Act), 1999. This circular clarifies the calculation method for compounding amounts, particularly in cases where foreign exchange laws are breached, such as delays in share allotments or …

RBI: The Reserve Bank of India (RBI) has issued circular that mainly focuses on the updated provisions related to compounding of contraventions under the FEMA (Foreign Exchange Management Act), 1999.(02.10.2024) Read More »

DGFT: Directorate General of Foreign Trade (DGFT)  has issued the notification to update the export policy for Halal-certified meat and meat products. Effective from October 16, 2024, the new rules require these products to be processed, produced, or packaged in facilities certified under the India Conformity Assessment Scheme (I-CAS) by the Quality Council of India (QCI).(02.10.2024)

Directorate General of Foreign Trade (DGFT)  has issued the notification to update the export policy for Halal-certified meat and meat products. Effective from October 16, 2024, the new rules require these products to be processed, produced, or packaged in facilities certified under the India Conformity Assessment Scheme (I-CAS) by the Quality Council of India (QCI). …

DGFT: Directorate General of Foreign Trade (DGFT)  has issued the notification to update the export policy for Halal-certified meat and meat products. Effective from October 16, 2024, the new rules require these products to be processed, produced, or packaged in facilities certified under the India Conformity Assessment Scheme (I-CAS) by the Quality Council of India (QCI).(02.10.2024) Read More »

DGFT:Directorate General of Foreign Trade (DGFT)  has issued the notification to impose a Minimum Import Price (MIP) on synthetic knitted fabrics.(02.10.2024)

DGFT Directorate General of Foreign Trade (DGFT)  has issued the notification to impose a Minimum Import Price (MIP) on synthetic knitted fabrics. This regulation extends the MIP requirement for specific fabric categories under various ITC (HS) codes until December 31, 2024. The fabrics affected include those made from synthetic fibers, such as unbleached, dyed, printed, …

DGFT:Directorate General of Foreign Trade (DGFT)  has issued the notification to impose a Minimum Import Price (MIP) on synthetic knitted fabrics.(02.10.2024) Read More »

DGFT: Directorate General of Foreign Trade (DGFT) has issued the notification which primarily addresses the extension of the RoDTEP (Remission of Duties and Taxes on Exported Products) scheme.(01.10.2024)

DGFT Directorate General of Foreign Trade (DGFT) has issued the notification which primarily addresses the extension of the RoDTEP (Remission of Duties and Taxes on Exported Products) scheme. Key points include: Extension of RoDTEP Scheme: For DTA (Domestic Tariff Area) Units, the scheme is extended until September 30, 2025. For AA (Advance Authorization), EOU (Export …

DGFT: Directorate General of Foreign Trade (DGFT) has issued the notification which primarily addresses the extension of the RoDTEP (Remission of Duties and Taxes on Exported Products) scheme.(01.10.2024) Read More »

GST: The CBIC has issued notification to appoint 1st April 2025 as the date from which the Authority referred to in section 171 shall not accept any request for examination as to whether input tax credits availed by any registered person or the reduction in the tax rate have actually resulted in a commensurate reduction in the price of the goods or services or both supplied by that registered person. (01.10.2024)

The CBIC has issued notification to appoint 1st April 2025 as the date from which the Authority referred to in section 171 shall not accept any request for examination as to whether input tax credits availed by any registered person or the reduction in the tax rate have actually resulted in a commensurate reduction in …

GST: The CBIC has issued notification to appoint 1st April 2025 as the date from which the Authority referred to in section 171 shall not accept any request for examination as to whether input tax credits availed by any registered person or the reduction in the tax rate have actually resulted in a commensurate reduction in the price of the goods or services or both supplied by that registered person. (01.10.2024) Read More »

GST: The CBIC has issued notification to provide that the Principal Bench of the Appellate Tribunal shall examine whether input tax credits availed by any registered person or the reduction in the tax rate have actually resulted in a commensurate reduction in the price of the goods or services or both supplied by that registered person. (01.10.2024)

GST The CBIC has issued notification to provide that the Principal Bench of the Appellate Tribunal shall examine whether input tax credits availed by any registered person or the reduction in the tax rate have actually resulted in a commensurate reduction in the price of the goods or services or both supplied by that registered …

GST: The CBIC has issued notification to provide that the Principal Bench of the Appellate Tribunal shall examine whether input tax credits availed by any registered person or the reduction in the tax rate have actually resulted in a commensurate reduction in the price of the goods or services or both supplied by that registered person. (01.10.2024) Read More »

Judicial Corner: GST: Where appeal filed by assessee beyond time limit prescribed under section 107(4) was dismissed as time barred, writ petition filed by assessee against same was to allowed as powers under article 226 are founded on justice, equity and good conscience and are exercised for public goods; Impugned order was to be set aside as provisions of section 107 could not be frustrated on mere technicalities and appeal was to be restored.(30.09.2024)

GST: HC can entertain writ petition against order passed by Joint Commissioner of CGST dismissing appeal as time barred: Where appeal filed by assessee beyond time limit prescribed under section 107(4) was dismissed as time barred, writ petition filed by assessee against same was to allowed as powers under article 226 are founded on justice, …

Judicial Corner: GST: Where appeal filed by assessee beyond time limit prescribed under section 107(4) was dismissed as time barred, writ petition filed by assessee against same was to allowed as powers under article 226 are founded on justice, equity and good conscience and are exercised for public goods; Impugned order was to be set aside as provisions of section 107 could not be frustrated on mere technicalities and appeal was to be restored.(30.09.2024) Read More »

DGFT: The export policy of Non-Basmati White rice (Semi-milled or wholly milled rice, whether or not polished or glazed: Other) under HS code 1006 30 90 is amended from ‘prohibited’ to ‘free’ subject to Minimum Export Price of USD 490/tonne with immediate effect and until further orders.(30.09.2024)

DGFT  The export policy of Non-Basmati White rice (Semi-milled or wholly milled rice, whether or not polished or glazed: Other) under HS code 1006 30 90 is amended from ‘prohibited’ to ‘free’ subject to Minimum Export Price of USD 490/tonne with immediate effect and until further orders. Notification No. 31/2024-25 dated 28.09.2024

GST: GSTN issued advisory on issuance of Notices/Orders without digital signatures of the issuing authorities(30.09.2024)

GSTN issued advisory on issuance of Notices/Orders without digital signatures of the issuing authorities The GSTN has issued an advisory regarding the validity of documents issued by the tax officers on the common portal viz. SCN/Orders without the Digital signatures on the pdf document downloaded from the common portal. In this context, it is to …

GST: GSTN issued advisory on issuance of Notices/Orders without digital signatures of the issuing authorities(30.09.2024) Read More »

Income Tax:  Considering the difficulties faced by taxpayers and other stakeholders in electronically filing various audit reports for Assessment Year 2024-25 under the Income Tax Act, the CBDT has extended the due date from 30-09-2024 to 07-10-2024.(30.09.2024)

Income Tax  Considering the difficulties faced by taxpayers and other stakeholders in electronically filing various audit reports for Assessment Year 2024-25 under the Income Tax Act, the CBDT has extended the due date from 30-09-2024 to 07-10-2024. Circular No. 10/2024 dated 29.09.2024

Judicial Corner: GST: Where show cause notice called as to why demand not be raised on account of inadmissible input tax credit, assessee responded stating it had not availed ITC in respect of said supplies, enclosed tabular statement setting out parties from whom availed inputs, response rejected by simply stating that reply was not satisfactory, order not informed by reason, entire purpose of order to bypass statutory period of limitation, impugned order passed under section 73 was to be stayed. (27.09.2024)

GST:  HC slams tax officials for passing unreasoned orders just to raise demand prior to expiry of limitation period: Where show cause notice called as to why demand not be raised on account of inadmissible input tax credit, assessee responded stating it had not availed ITC in respect of said supplies, enclosed tabular statement setting …

Judicial Corner: GST: Where show cause notice called as to why demand not be raised on account of inadmissible input tax credit, assessee responded stating it had not availed ITC in respect of said supplies, enclosed tabular statement setting out parties from whom availed inputs, response rejected by simply stating that reply was not satisfactory, order not informed by reason, entire purpose of order to bypass statutory period of limitation, impugned order passed under section 73 was to be stayed. (27.09.2024) Read More »

Judicial Corner: Penalty is imposable but to be reduced when no case is made out against importer in case of plastic scrap and he has come forward to redeem plastic granules on payment of redemption fine and payment of relevant Customs duty. (26.09.2024)

CUSTOMS:  No confiscation of goods if importer proved by documentary evidence that goods were legally procured: Penalty is imposable but to be reduced when no case is made out against importer in case of plastic scrap and he has come forward to redeem plastic granules on payment of redemption fine and payment of relevant Customs …

Judicial Corner: Penalty is imposable but to be reduced when no case is made out against importer in case of plastic scrap and he has come forward to redeem plastic granules on payment of redemption fine and payment of relevant Customs duty. (26.09.2024) Read More »

Judicial Corner: ST : Reimbursable expenses, merely allocated by book entries for internal project allocation purposes and not received or recovered from any person, cannot be considered as taxable for service tax purposes. (25.09.2024)

EXCISE AND SERVICE TAX: No ST on reimbursable expenses merely allocated by book entries for internal project allocation purposes: HC ST : Reimbursable expenses, merely allocated by book entries for internal project allocation purposes and not received or recovered from any person, cannot be considered as taxable for service tax purposes. ST : In order …

Judicial Corner: ST : Reimbursable expenses, merely allocated by book entries for internal project allocation purposes and not received or recovered from any person, cannot be considered as taxable for service tax purposes. (25.09.2024) Read More »

SEBI: SEBI has issued an updated master circular on ‘Surveillance of Securities Market’.(25.09.2024)

SEBI SEBI has issued an updated master circular on ‘Surveillance of Securities Market’. This master circular consolidates all the circulars pertaining to the surveillance of the securities market at one place. This Master Circular is categorised subject-wise under various headings, viz., trading rules and shareholding in dematerialized mode, and monitoring of unauthenticated news circulated by …

SEBI: SEBI has issued an updated master circular on ‘Surveillance of Securities Market’.(25.09.2024) Read More »

GST: Frequently Asked Questions on IMS(25.09.2024)

GST Advisory Frequently Asked Questions on IMS With the Introduction of Invoice Management System (IMS), the taxpayer’s interaction with invoices and business processes will change. Now, the GSTN has issued an update on frequently asked questions (FAQs) on IMS to get a better understanding of the new functionality.  

Judicial Corner: GST:  Matter to be remanded since SCN was uploaded on GST portal under ‘View Additional Notices & Orders’ tab: HC Where show cause notice was uploaded on GST portal in category of ‘View Additional Notices & Orders’ and same was not easily accessible by assessee, impugned order passed under section 73 was to be set aside and matter was to be remanded.(24.09.2024)

GST:  Matter to be remanded since SCN was uploaded on GST portal under ‘View Additional Notices & Orders’ tab: HC Where show cause notice was uploaded on GST portal in category of ‘View Additional Notices & Orders’ and same was not easily accessible by assessee, impugned order passed under section 73 was to be set …

Judicial Corner: GST:  Matter to be remanded since SCN was uploaded on GST portal under ‘View Additional Notices & Orders’ tab: HC Where show cause notice was uploaded on GST portal in category of ‘View Additional Notices & Orders’ and same was not easily accessible by assessee, impugned order passed under section 73 was to be set aside and matter was to be remanded.(24.09.2024) Read More »

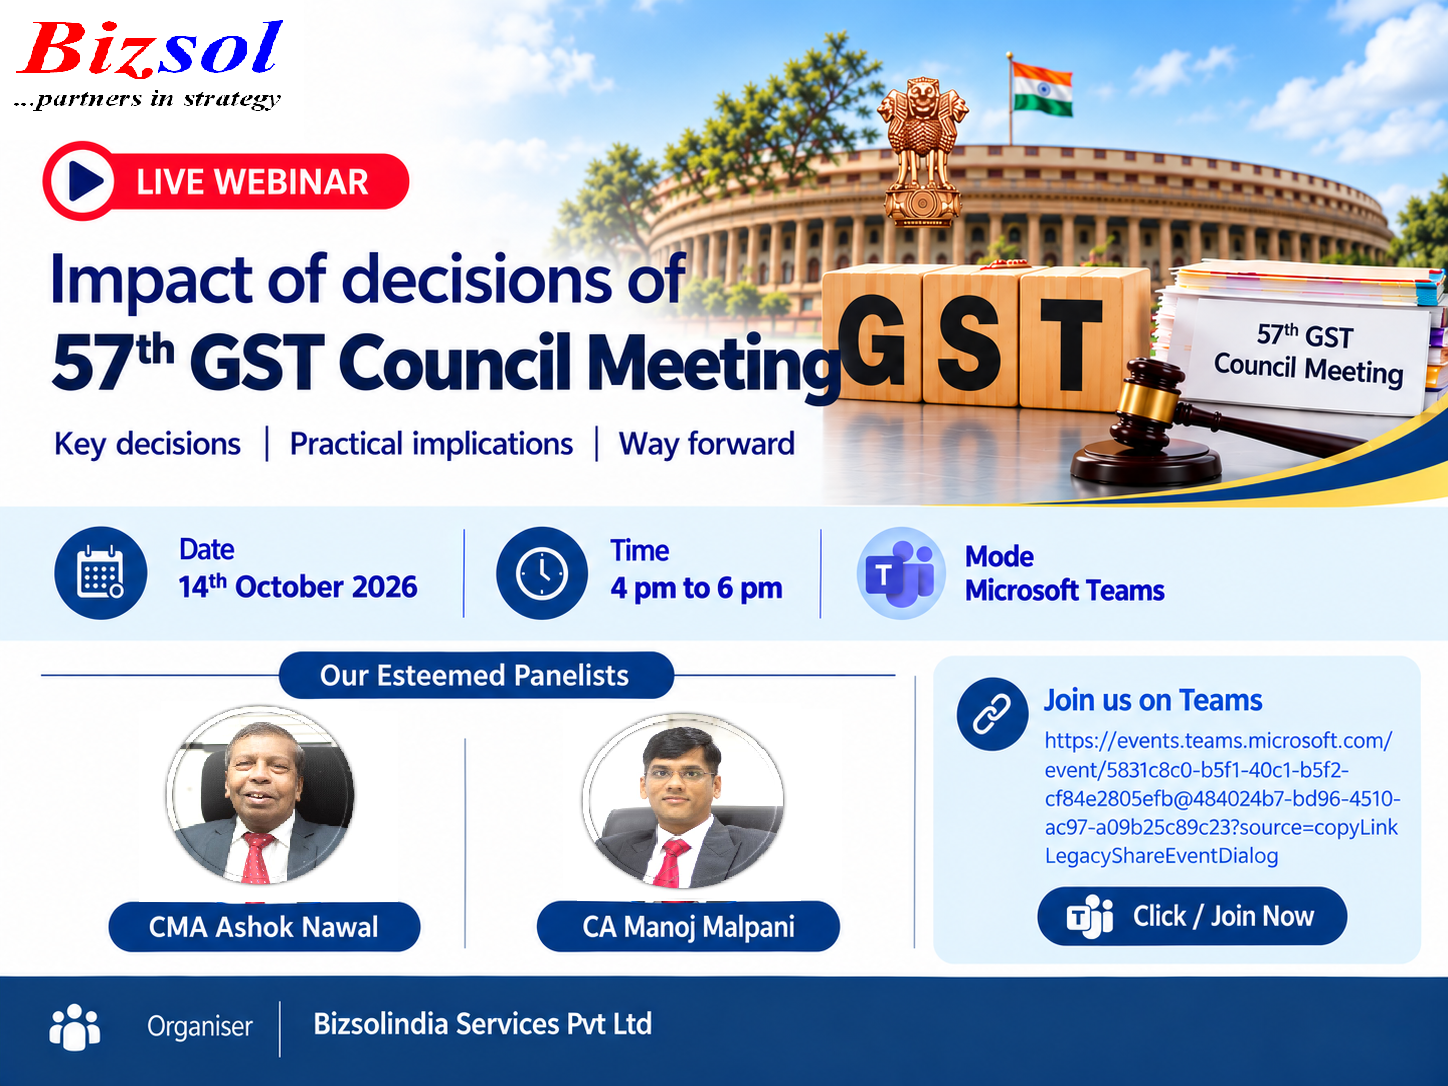
webinar on “Impact of Decisions of the 57th GST Council Meeting” on 14th October 2026 at 4:00 PM to 6:00 PM

Click Here for Registration

This will close in 20 seconds

Bizsol ProfileContactUseful LinksSubscribe